Author: minaseddighfinancial-com

  • Estate Planning for Business Owners

    Estate Planning for Business Owners

    As a financial advisor working with entrepreneurs across British Columbia, I see firsthand how estate planning forms the backbone of a lasting business legacy. For business owners, having a clear plan—including wills, trusts, and a well-structured succession roadmap—is essential to ensure your business continues smoothly when leadership changes hands. Tax implications and carefully crafted exit strategies play a pivotal role in maximizing the value you’ve built and protecting your hard-earned assets. Thoughtful estate planning isn’t just about the future—it's a key part of building resilient businesses today.

    Continue to full article

  • How Disability Insurance Builds Professional Credibility

    How Disability Insurance Builds Professional Credibility

    As someone passionate about helping both individuals and businesses achieve steady growth, I often recommend strategies that go beyond simple investment planning. Disability insurance is a key component in building true financial security—not only does it safeguard income during unexpected events, but it also sends a strong signal of stability and reliability. For business owners, offering disability insurance can be a powerful way to attract and retain top talent, while for professionals, it demonstrates a commitment to long-term success and trustworthiness. By prioritizing this important coverage, we enhance our professional credibility and reinforce the foundation for lasting growth—something I value deeply in my advisory approach.

    Continue to full article

  • Why Mortgage Insurance Knowledge Adds Career Depth

    Why Mortgage Insurance Knowledge Adds Career Depth

    One area I often emphasize with clients and colleagues alike is the importance of truly understanding mortgage insurance. This coverage is designed to protect lenders if borrowers default, but for those of us in financial services, building a strong grasp of its many products, current regulations, and evolving trends adds a valuable layer of expertise. It’s not just about compliance or managing risk—it's about deepening client trust and expanding our own capacity to guide individuals and businesses toward smarter decisions. In my advisory work, I’ve seen how this depth of knowledge supports both career growth and the quality of service we offer.

    Continue to full article

  • RRIF Minimums Get Pricier When You Wait

    RRIF Minimums Get Pricier When You Wait

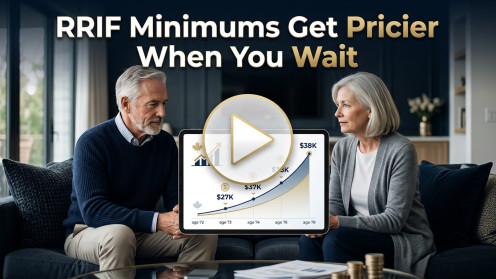
    Many Canadians may not realize how waiting to convert an RRSP to a RRIF can affect their retirement income. By December 31 of the year you turn 71, your RRSP must be closed—often rolling into a RRIF, which comes with minimum annual withdrawals that are taxed. These withdrawals are calculated from your account value as of January 1 and your age, starting at around 5% and climbing to almost 20% by age 95. For example, a $500,000 RRSP growing at 5% annually over seven years could reach about $704,000, meaning your minimum withdrawal at age 72 jumps to nearly $38,000—much higher than the $27,000 you’d withdraw if you converted earlier. This extra taxable income becomes even more important when you factor in CPP, OAS, workplace pensions, and investment earnings, especially since the OAS recovery tax kicks in above $95,000 in 2026. As someone who guides clients through retirement planning, I often recommend strategies like taking partial withdrawals during lower-income years, using pension income splitting, considering a younger spouse’s age for RRIF calculations, and making the most of TFSA contributions. These steps can help you spread out your taxes and make your retirement income work smarter for you.

  • British Columbia Tariff Support Expands

    British Columbia Tariff Support Expands

    Important news for small and medium-sized businesses in British Columbia: the province’s tariff-response program is expanding to provide additional support for firms navigating the pressures of international tariffs and ongoing trade disruptions. As a financial advisor based in Coquitlam, I see firsthand how liquidity challenges can impact business operations—especially when markets shift unexpectedly. This expanded support is designed to help protect Canadian jobs and local industries, while strengthening our supply chains so that businesses like yours can continue to operate and adapt during these uncertain times.

    The funding offers opportunities for businesses to boost productivity, reduce costs, and build more resilient supply chains, all while exploring new markets for future growth. Support may come directly to your business or through organizations committed to helping you navigate global trade changes and reinforce domestic trade connections.

    If your business is considering applying, a strong plan to pivot operations toward new growth paths is essential, though some of the implementation details are still pending. I’m always committed to sharing resources that can help you achieve both stability and growth, even when the economic landscape is shifting.

  • Financial Planning: Quick Tips to Build Wealth Early

    Financial Planning: Quick Tips to Build Wealth Early

    As someone who’s spent years guiding clients through their financial journeys, I know first-hand how a solid financial plan can set the stage for both security and opportunity. Think of financial planning as your personalized roadmap—it’s about more than just numbers; it’s about designing a life where your goals are truly within reach, and financial worries don’t hold you back.

    A comprehensive plan covers every major area: from budgeting and saving, to investing, debt management, retirement strategies, taxes, insurance, and even estate planning. I always encourage breaking down those big, sometimes intimidating goals—like building wealth or preparing for retirement—into smaller, actionable steps. This approach not only makes progress feel achievable, but also helps reduce overwhelm along the way.

    Starting early plays a huge role. Building up your savings, tackling high-interest debt, and maintaining an emergency fund are all foundational habits that can help you weather life’s unexpected turns.

    And to accelerate your path to wealth, consider smart investing, staying diversified, making the most of retirement savings options, and keeping an eye out for additional income streams. These are the same strategies I share with individuals and businesses looking to secure their financial future—because building wealth is a journey, and every step counts.
  • How Experienced Agents Help Shape New Professionals

    How Experienced Agents Help Shape New Professionals

    One of the most rewarding aspects of my role as a financial advisor is guiding emerging professionals as they step into the industry. Seasoned advisors have a unique opportunity to mentor new talent by sharing not only technical knowledge but also the values and ethical standards that are essential in our field. I’ve seen firsthand how this transfer of expertise helps new professionals strengthen their negotiation, client service, and communication abilities—key skills that support both personal growth and resilience. By fostering a collaborative environment grounded in best practices, we help shape a culture of continuous improvement and teamwork, ultimately paving the way for long-term success in financial services.

    Continue to full article

  • Six tips for managing your cash flow

    Six tips for managing your cash flow

    Managing cash flow well is at the heart of financial stability, whether for an individual or a business. Having worked closely with clients on everything from investment strategies to planning for retirement, I’ve seen firsthand that poor cash flow management can quickly lead to debt dependence and higher interest expenses—often signaled by cash shortages and late payments. To avoid these pitfalls, it’s crucial to forecast your income and expenses, keep a close eye on receivables and payables, and regularly analyze your cash flow. These steps not only help reduce costs but also lay the groundwork for long-term growth. Taking control of your cash flow is one of the most empowering financial habits you can build.

    Continue to full article

  • No-Fee High-Interest Savings Accounts in Canada

    No-Fee High-Interest Savings Accounts in Canada

    High-Interest Savings Accounts (HISAs) in Canada continue to be a smart way to grow your cash without sacrificing accessibility. With rates ranging from approximately 1.5% to 4%, these accounts offer a variable premium above what you’d find in regular savings, making them ideal for those focused on preserving capital while earning daily interest. For clients who want a safe place for emergency funds or have extra cash after maximizing their registered accounts, HISAs can be a practical fit. The five no-fee options recently highlighted all come with no minimum balance, unlimited transactions, no transfer fees, and deposit insurance—key features I look for when guiding clients on liquidity solutions. While promotional rates may catch your eye, it’s the base rate and overall account conditions that tend to matter most over the long run. When considering a HISA, I always encourage looking beyond just the headline rate: think about fees, insurance, and how accessible your funds will be, especially if you’re building up savings for a home down payment or keeping reserves for future opportunities. As part of my approach to financial education, I believe understanding these details can make your money work smarter for you.

  • Grocery Bills Stall RESP Saving

    Grocery Bills Stall RESP Saving

    Balancing everyday expenses like groceries can make it tough for families to prioritize RESP savings. According to a recent survey, while half of Canadian parents have opened an RESP, nearly as many—45%, including parents with older children—wish they had started sooner. It's clear that post-secondary education is seen as essential for long-term financial security by 84% of Canadians, yet 51% of parents are feeling anxious about their finances. Rising grocery bills (noted by 60% of parents), lagging salaries (47%), and housing costs (41%) are the main hurdles to saving for education. The challenge doesn’t end there: 60% call education savings difficult, 70% find major purchases a stretch, and 68% say retirement saving is tough. As a Financial Advisor with a passion for financial education, I always encourage families to have ongoing conversations about their education savings goals—not only within the household, but also with relatives and trusted professionals. There are government grants and incentives designed to support modest-income families across Canada, and understanding these options can make a real difference for your children’s future.