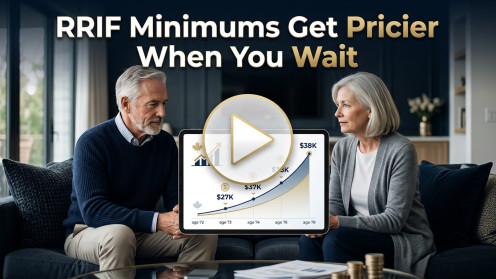
Many Canadians may not realize how waiting to convert an RRSP to a RRIF can affect their retirement income. By December 31 of the year you turn 71, your RRSP must be closed—often rolling into a RRIF, which comes with minimum annual withdrawals that are taxed. These withdrawals are calculated from your account value as of January 1 and your age, starting at around 5% and climbing to almost 20% by age 95. For example, a $500,000 RRSP growing at 5% annually over seven years could reach about $704,000, meaning your minimum withdrawal at age 72 jumps to nearly $38,000—much higher than the $27,000 you’d withdraw if you converted earlier. This extra taxable income becomes even more important when you factor in CPP, OAS, workplace pensions, and investment earnings, especially since the OAS recovery tax kicks in above $95,000 in 2026. As someone who guides clients through retirement planning, I often recommend strategies like taking partial withdrawals during lower-income years, using pension income splitting, considering a younger spouse’s age for RRIF calculations, and making the most of TFSA contributions. These steps can help you spread out your taxes and make your retirement income work smarter for you.
Leave a Reply